MortgageWise Newsletter – Fall 2026
Published by Myers Capital Hawaii
Mortgage News and Updates – Fall 2026
Get the latest mortgage industry news. Read the Fall 2026 MortgageWise newsletter (PDF). The PDF retains the original edition; the web article below includes sourced clarifications reviewed November 11, 2026.
-Mortgage Rate Outlook: Look Deeper – The Buyer’s Market Emerges
-Your Credit Score Now Has Some Competition
-The Return Of The Negotiating Buyer
-Can Part of Your Home Help You Qualify for It?
-Buying a Home From Family? Consider a Gift of Equity.
Mortgage Rate Outlook: Look Deeper – The Buyer’s Market Emerges
For homebuyers hoping 2026 would bring substantially lower mortgage rates, the year has delivered a frustrating reversal. After the average 30-year fixed rate briefly dipped below 6% earlier this year, rates climbed through the summer and accelerated in September. Freddie Mac’s Primary Mortgage Market Survey archive reported a U.S. 30-year fixed average of 7.28% on October 1, 2026. This historical national survey average is not a current rate quote or an offer to an individual borrower.
Why did rates move higher? Mortgage rates are driven primarily by the bond market, particularly mortgage-backed securities and longer-term U.S. Treasury yields. Persistent inflation, resilient economic growth and concerns about government borrowing have all contributed to investors demanding higher yields. The U.S. Treasury daily par-yield table recorded a 10-year yield of 5.31% on October 5, 2026. This is a dated Treasury yield, not a mortgage rate.
Your Credit Score Now Has Some Competition
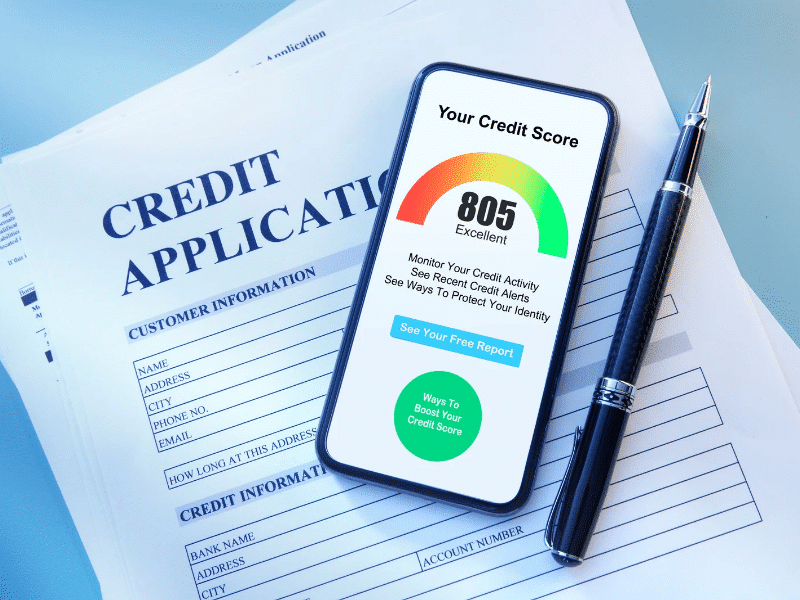
Approved lenders can use VantageScore 4.0 for eligible mortgages under the agencies’ rollout rules. Fannie Mae permits approved lenders to use it for eligible Desktop Underwriter loans; Freddie Mac is using a limited rollout for approved sellers. Classic FICO remains an option. Availability depends on the lender and loan; this does not establish that every lender or every Myers Capital program offers VantageScore underwriting.
Why does that matter? VantageScore 4.0 evaluates credit differently and incorporates newer information, including trended credit data and on-time rent payment history. That may provide a more complete picture for some borrowers, particularly those with limited traditional credit histories.
It doesn’t mean everyone will suddenly have a higher score—or that FICO is going away. Lenders can continue using Classic FICO, and eligibility and underwriting requirements still apply.
The takeaway? Your credit profile may no longer tell just one story. If you’ve been concerned that your credit history could stand between you and homeownership, talk with us. It’s worth taking a fresh look.
The Return of the Negotiating Buyer
For years, buying a home often meant acting quickly, competing against multiple offers and asking for as little as possible from the seller. Today’s market looks very different. Higher mortgage rates have sidelined some buyers, while the supply of homes for sale has increased.
Buyers who now enter the market may have something valuable on their side: negotiating power. Redfin’s August 2026 U.S. report found that 59.5% of homes sold below their original asking price. Separately, Redfin reported seller concessions in 44.7% of transactions reported by its buyers’ agents over the three months ending August 31, 2026. That concession measure excludes negotiated price reductions. These national figures describe different measures and do not establish conditions for a particular Hawaii property.
Look Beyond the Purchase Price
When negotiating, it’s natural to focus on getting the seller to accept a lower price. But a price reduction isn’t always the only—or even the most valuable—way to improve the deal.
Suppose you’re buying a $500,000 home and the seller is willing to give up $10,000 to make the transaction happen. You might negotiate a lower purchase price, but a modest reduction in purchase price may make only a small difference in the monthly payment.
Alternatively, depending on your loan and circumstances, some or all of that value could potentially be applied toward allowable closing costs. It could fund part of a mortgage-rate buydown—discount points that either permanently reduce the interest rate or temporarily reduce the rate during the first one to two years of the loan. Each solves a different problem, making it worthwhile to compare the numbers.
Either of these could potentially have a greater impact on your immediate cash needs or monthly budget, and could potentially alleviate budget pain long enough for a refinance to look attractive, should rates cooperate.
Negotiate With a Plan
Price isn’t the only item on the negotiating table. Depending on the property and local market, buyers may also negotiate repairs, credits, closing timelines or other terms. The key is knowing which concession is most valuable to you—ideally before the offer is written. A buyer with plenty of savings but a tight monthly budget may have different priorities than someone who can comfortably afford the payment but wants to preserve cash for moving and other expenses.
Conditions also vary considerably from one market—and even one neighborhood—to another. Some homes still attract strong competition, while properties that have been on the market longer may give buyers considerably more room to negotiate.
Put Your Financing Into the Negotiation
That’s why we should be part of the conversation early. Before deciding whether to ask for a price reduction, closing-cost assistance or a rate buydown, we can run the numbers and develop a strategy. Loan programs usually place limits and requirements on seller contributions, so it’s important to know beforehand what’s possible.
Today’s higher rates have made buying more challenging—but they’ve also changed the balance between buyers and sellers. If you find the right home, don’t just ask whether you can afford the asking price. Ask how the entire transaction can be structured to work better for you—and put our experience to work!
Can Part of Your Home Help You Qualify for it?
With home prices and mortgage rates still elevated, buyers are looking for new ways to make homeownership more affordable. One possibility may be hiding within the property itself: rental income.
Buying a duplex, triplex or four-unit property—or a single-family home with an accessory dwelling unit (ADU)—can provide a home and a source of income. Under certain circumstances, some of that income can potentially be used when qualifying you for the mortgage.
Live in One, Rent the Other
Consider buying a duplex, living in one unit and renting the other. The additional unit may generate income to offset the property’s higher cost. Depending on the loan program, eligible rental income may also help you qualify for the mortgage.
That changes the affordability equation. Instead of looking only at your employment income, you’re also considering what the property itself may contribute each month. The same concept can extend to triplexes and four-unit properties.
Don’t Overlook the ADU
An accessory dwelling unit (ADU) may provide eligible rental income, but agency rules differ. Fannie Mae guidance covers an existing ADU on a one-unit principal residence for eligible purchase or limited cash-out transactions, with ADU income capped at 30% of total qualifying income. Freddie Mac’s February 2026 ADU fact sheet separately addresses purchase and no-cash-out refinancing of a one-unit primary residence: lease-based qualifying rent is limited to 75% of the lease amount, and ADU income to 30% of total qualifying income. Appraisal, zoning, documentation and applicable landlord-education requirements still apply. These limits are not a blanket rule for every rental property or loan program.
It’s Not as Simple as “I’ll Rent a Room”
Lenders can’t simply count whatever rent a buyer expects to collect. Rental income must meet specific loan-program and documentation requirements. And planning to rent a bedroom generally isn’t the same as purchasing a property with a qualifying rental unit. That’s why an income-producing property is worth discussing with us before deciding whether it’s within reach. We can determine whether the property and anticipated rental income may qualify—and how much can actually be used.
In today’s affordability-challenged market, sometimes the answer isn’t simply finding a less expensive home. It may be finding a home that helps pay for itself.
Buying a Home From Family? Consider a Gift of Equity
A “gift of equity” occurs when a family member sells a home for less than its market value and gifts some of the difference to the buyer.
Here’s an example: Suppose your parents own a home worth $500,000 and agree to sell it to you for $450,000.
That $50,000 difference can be structured as a gift of equity and used toward down payment or closing costs, depending on the loan program. The strategy can keep a valued home within the family, making homeownership an option for a buyer who might not otherwise be able to purchase a home, and it can potentially help the buyer avoid private mortgage insurance.
Structure the Sale Before You Sign
Gift-of-equity transactions have specific rules, and eligible relationships (generally family-only), documentation and allowable uses can vary by loan program. A gift is generally not income to the recipient, but the donor may need to file a gift-tax return even when no gift tax is payable. Filing requirements depend on the circumstances; do not assume every gift requires a return or creates a tax bill. Review the IRS gift-tax guidance with a tax adviser, including any sale, capital-gain and tax-basis consequences.
That’s why it’s important to involve us before agreeing on the sales price or developing the contract. We can help determine whether a gift of equity is available and how the transaction should be structured.
If a home may be changing hands within your family, the equity already in the property could help make the purchase possible. Give us a call to discuss your options.
Copyright © 2026 Myers Capital Hawaii