How Do Ground Up Construction Loans Work
Published by Myers Capital Hawaii
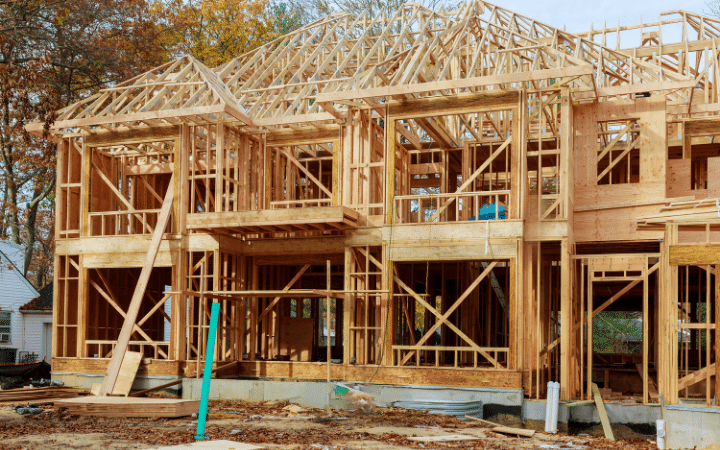
How does a construction loan work?
A construction loan finances an approved building project, with funds typically released in stages as work progresses. Before closing, the lender reviews the project budget, plans, builder, property and repayment strategy. The draw process and loan agreement determine when funds are available and what documentation is required.
For a Hawaii project, start with the property location, permit status, construction budget and expected completion date. Ground-up development, renovation and work already underway can require different financing structures.
How Do Ground-Up Construction Loans Work? The Basics
Even though the specifics can become complicated, as is often the case with many types of real estate loans, the basic idea behind construction loans is pretty simple.
They are short-term loans used to cover the cost of the construction process. Construction loans can be used for new construction projects, rehabs of existing properties, and to provide the funding needed to complete in-progress work for either of these projects.
The key benefit for real estate investors is the ability to change and improve one or many buildings in a way that aligns with the needs and desires of the local market, tapping into the specifics sought by that renters or buyers.
The properties are often multi-family residences, but single-family homes developed as investment properties can use construction loans as well.
These loans are short-term loans, intended to pay for the costs of construction. They are not permanent mortgages, but rather temporary financing designed specifically for the building phase.
 What Are Reimbursable Draws for Construction Loans?
The money provided by a ground-up construction loan is generally disbursed as a series of draws as construction progresses, and not as a lump sum. The borrower pays for and completes the work, then the lender provides reimbursement.
This process normally follows a draw schedule. In this structure, specific construction milestones are set. Once a milestone is reached, the contractor requests a draw, and the investor passes that request onto the lender.
The lender then conducts a review to verify that the requested funds align with the completed work. Once approved, the lender disburses the funds and makes the related payments.
Interest accrual, payment dates and draw treatment are specified in the loan agreement. Some loans require monthly interest payments during construction; an agreed interest reserve may fund payments for a limited period. A reserve does not eliminate interest or guarantee that it will cover delays. Confirm the first payment date, how interest is calculated on advances, and who pays if the reserve is exhausted.
How commercial construction loan draws work in Hawaii
A construction loan draw is a release of part of the loan funds as work progresses. The draw schedule ties requests to the approved budget and construction milestones. Before closing, ask when the first draw can be requested, how often you can submit requests, and what the lender needs before releasing funds.
Build the draw schedule around your project
Start with the contractor's schedule of values and project timeline. Map line items such as site work, foundation, framing, and finishes to the points when your contractor expects payment. Compare that schedule with your lender's draw process. Ask how the lender handles deposits, materials stored off site, and any funds held until completion.
On a Hawaii project, ask the contractor to identify materials that need to ship from another island or the mainland. If an order requires a deposit before delivery, confirm how you'll pay it and whether the lender will consider it in a draw. Plan for a gap between an invoice due date and the release of loan funds.
Prepare each request
A draw package may include the requested amount by budget line, invoices, change orders, photos or inspection records, and lien waivers where applicable. Confirm the exact list with your lender. Keep a running record of approved draws, the balance available in each budget line, and the amount still required to complete the work.
If a change order affects the cost or timeline, raise it before the next request. Ask whether the lender needs to approve the change and how it affects the remaining loan funds. Keep a separate record of contingency spending so you can see how much cushion is left.
Plan for the last draw and repayment
Ask what must be in place before the final release. Depending on the project and loan, that might include a final inspection, closeout records, or proof that required approvals are in place. Review your repayment plan before construction begins and revisit it if the project timeline changes.
Bring your project budget, plans, schedule, and permit status when you discuss commercial ground-up construction financing.
Loan-to-cost and loan-to-after-repair-value
Loan-to-cost (LTC) = loan amount ÷ total project cost × 100. Confirm which acquisition and construction costs the lender includes.
Loan-to-after-repair-value (LTARV) = loan amount ÷ supported after-repair value × 100. For ground-up development, the lender may instead describe the valuation as the property's as-completed value. Cost and completed value are different measures.
For illustration, a $600,000 loan against an $800,000 total project cost is 75% LTC. If the supported completed value is $1,000,000, the loan-to-completed-value ratio is 60%. These figures explain the arithmetic; they are not quoted lending limits or an approval standard.
What Do Construction Loans Cover?
Construction loans can be used to pay for labor costs, materials, permitting, and the land itself (yes, a construction loan does include the land – or can, at least).
The approval process is detailed and requires in-depth documentation from the investor. However, an approved construction loan will cover a wide range of costs related to the project.
 What are the Benefits of Construction Loans?
The foundational benefit of a construction loan is to build a new property that taps into the wants and needs of the local housing market. Or, to renovate and repair an existing property so that it can better align with those wants and needs. A more desirable property can lead to a higher sale price or higher rents, improving ROI for the investor.
Other key benefits of construction loans include their ability to cover all phases of the project with a single loan, making financing simpler for the investor. Crucially, these loans normally feature interest-only payments during active construction, providing financial flexibility over the course of the project.
Some lenders also offer flexible loan term options and payment schedules to better support the changing timelines common in construction project.
Managing the Costs of Construction Loans
Build a financing budget that separates construction costs from loan costs. Ask about origination charges, interest, draw or inspection fees, reserves, and any extension costs. Confirm how interest is calculated, when payments start, and how overruns will be funded. These terms depend on the loan agreement; do not assume every construction loan converts automatically to permanent financing.
What Happens After Construction is Completed?
To address the cost of the loan after construction is completed, borrowers can:
– Take out a construction loan that automatically converts to a mortgage at the end of its term.
– Sell the property and pay off the construction loan with the proceeds.
– Refinance into a long-term loan.
– On larger development projects with multiple phases, the construction loan could be modified to provide additional construction funds. In addition, on larger projects, some of the already built structures could be sold and used to pay down the loan.
– If the borrower can’t pay the full loan balance directly, they can secure long-term financing. This also helps to address the higher interest rates that often come with short-term loans like construction loans.
 How to Qualify for a Construction Loan
How hard is it to get a construction loan? The standards are higher than those of a conventional mortgage, for example, but are by no means impossible to meet for stable and established real estate investors.
There are normally three major phases in the construction loan application process:
1. A pre-qualification phase that includes a builder assessment, where the lender determines if the builder attached to the project meets the lender’s standards.
2. Documentation submission and review, where the borrower submits detailed project information (such as budgets, project plans, and contracts with the builder) and the lender makes sure these documents align with their standards.
3. Approval, followed by the release of funds based on the project reaching defined construction milestones.
What are the requirements for a construction loan? Exact details vary between lenders, but financial requirements relative to the loan amount are foundational. Lenders are less likely to offer loans to prospective investors who have inconsistent credit histories, significant outstanding debt, and other large financial obligations.
Construction loans are typically secured by the property, including the land and improvements. The lender also evaluates completion risk, the budget, borrower qualifications and the proposed repayment plan. Collateral does not remove the need for underwriting.
More unique requirements include the need for a qualified, licensed, and experienced builder to be part of the project.
Borrowers will have to show they have a contract with the builder to complete the project. Additionally, deep details about the project itself are needed. That includes an in-depth breakdown of construction costs and pricing, the construction plans, the timeline, and more.
Securing Your Construction Loan as a Real Estate Investor
Construction loans require careful planning, assets that align with lender expectations, an established relationship with a qualified builder, and a detailed plan for the project.
With those pieces in place, a construction loan can certainly pay off in the long run. Real estate investors can use the funds the loan provides to build attractive, durable, and dependable investment properties. That can mean long-term revenue from renters as well as a valuable asset within the investor’s portfolio.
Looking for a construction loan lender? Myers Capital offers both ground-up and mid-construction lending options to get projects across the finish line and turn them into revenue-generating properties. Our approach includes no personal income verification, loan amounts up to $5 million, and the ability to transition to long-term financing.
Myers Capital believes in forming true partnerships with our clients, providing guidance and advice to help them achieve their goals. Why? Because your success is our success.
Learn more about our loans for commercial property investors.
Copyright © 2025 Myers Capital Hawaii
Explore financing for your construction project
Review our commercial ground-up construction loans. For an existing property that needs improvements, explore bridge loans with rehab, or discuss your project with our team.